Is the Reliability of Public Opinion Surveys Declining?

Public opinion surveys provide a wealth of information about beliefs in America and around the world. For example, they document how much public approval for same-sex marriage has been increasing, how Facebook has infiltrated many of our daily lives, and how humanitarian aid affects how citizens of other nations view America.

But pollsters face a significant challenge. As the Pew Research Center for the People & the Press notes in a new study, survey response rates continue to plummet:

Fifteen years ago, more than one in three of households responded to surveys. Today, that rate is less than one in ten.

That increases the cost of reliable surveys — to get a reasonable sample, you need to try to contact more households. Even more important, declining participation raises the question of whether the minority of respondents are representative of the population as a whole. The Pew Research Center study took a close look at that question:

The general decline in response rates is evident across nearly all types of surveys, in the United States and abroad. At the same time, greater effort and expense are required to achieve even the diminished response rates of today. These challenges have led many to question whether surveys are still providing accurate and unbiased information. Although response rates have decreased in landline surveys, the inclusion of cell phones – necessitated by the rapid rise of households with cell phones but no landline – has further contributed to the overall decline in response rates for telephone surveys.

A new study by the Pew Research Center for the People & the Press finds that, despite declining response rates, telephone surveys that include landlines and cell phones and are weighted to match the demographic composition of the population continue to provide accurate data on most political, social and economic measures. This comports with the consistent record of accuracy achieved by major polls when it comes to estimating election outcomes, among other things.

This is not to say that declining response rates are without consequence. One significant area of potential non-response bias identified in the study is that survey participants tend to be significantly more engaged in civic activity than those who do not participate, confirming what previous research has shown. People who volunteer are more likely to agree to take part in surveys than those who do not do these things. This has serious implications for a survey’s ability to accurately gauge behaviors related to volunteerism and civic activity. For example, telephone surveys may overestimate such behaviors as church attendance, contacting elected officials, or attending campaign events.

However, the study finds that the tendency to volunteer is not strongly related to political preferences, including partisanship, ideology and views on a variety of issues. Republicans and conservatives are somewhat more likely than Democrats and liberals to say they volunteer, but this difference is not large enough to cause them to be substantially over-represented in telephone surveys.

In short, opinion surveys likely overstate civic activity, but otherwise appear to track other observable political, social, and economic variables.
Fixing Medicare’s Double-Counting Problem

Last week I argued that budgeting for Medicare’s hospital insurance program is flawed. Today, I offer two ways to fix it (and reject a third).

Medicare Part A is one of several federal programs that control spending through a “belt and suspenders” combination of regular program rules (the belt) and an overall limit (the suspenders). But it’s the only one that allows legislated savings to offset the costs of policy changes in other programs and extend the time before the overall limit constrains operations.

Congress can’t increase Social Security payroll taxes to pay for increased health care spending or reduce flood insurance subsidies to pay for tax cuts; in both cases, the resources stay within the affected programs. And when it cuts spending on Medicare Parts B and D to pay for other spending, no one claims those cuts will also postpone the day when trust fund exhaustion will disrupt their operations.

Such double counting is possible only in Medicare Part A. And it’s a real problem, creating needless confusion and reinforcing the sense that Washington plays fast and loose with budget numbers.

Happily, Congress knows how to fix this problem. All it needs to do is apply to Medicare A the practices used by one of the other programs that have “belt and suspenders” budgeting but avoid potential double counting.

One approach would be the rules used by the National Flood Insurance Program. As I discussed in more detail last week, those rules require that any legislated savings remain in the program. Lawmakers can’t reduce NFIP subsidies to pay for new spending in other programs. Instead, any savings are automatically earmarked to pay future NFIP claims that would go unpaid because of the program’s borrowing limit. (For an example, see here.)

This approach brings the overall limit explicitly into the budget. But it makes for weird budgeting. For example, the budget baseline would show Medicare A breaking even over the long run, since the trust fund limit would take precedence over its fundamental deficits.

A better approach would adopt the rules used by Social Security. Those rules show Social Security running deficits far into the future in the budget baseline, but they still take the trust fund seriously when examining new legislation. Any proposed cuts to the program’s spending or increases in its revenues are “off budget”. The Congressional Budget Office reports them, but Congress can’t use them to pay for other spending.

A recent Senate bill provides a telling example. The bill would expand the type of income subject to payroll taxes in order to pay for a one-year extension of low interest rates on student loans. Those low rates would cost $6 billion, but the Senate proposal would raise $9 billion. The bill had to overshoot that much because $3 billion comes from higher Social Security taxes and is thus off limits. Meanwhile, the $6 billion in usable revenues comes from Medicare Part A, which is considered “on budget” despite having a trust fund just like Social Security’s.

That difference highlights the inconsistency in current budgeting. If policymakers believe the Part A trust fund is as sacrosanct as Social Security’s, they should provide the same budgetary protection: Part A savings should be off budget, where they couldn’t be used to pay for health reform, student loans, tax cuts, or anything else outside the hospital insurance program.

If Congress doesn’t believe the trust fund deserves that protection, it should adopt a third approach: make the Part A fund as operationally toothless as the one for Medicare B and D. Those programs spend much more than they receive, so their trust fund has unlimited ability to draw on general revenues. If the same were true for Medicare Part A, program changes could be used to pay for health reform (as they were in 2010) or anything else, just like any other mandatory program. But we wouldn’t have any confusion over whether those changes also extend the program’s ability to operate.

The Social Security and Medicare B and D approaches both make more sense than the mishmash that applies to Medicare A today. I think the Medicare B and D approach is the better of the two, not least because it would put all the parts of Medicare on equal footing. But one could certainly argue for the Social Security approach instead. That’s the discussion we should have now so that we can avoid needless double-counting debates in the future.

P.S. Several readers noted an important qualification to my Social Security discussion in my earlier post. Many experts believe past Social Security surpluses have been used to finance deficits in the rest of the budget and, as a result, Social Security resources have been paying for higher spending or lower revenues elsewhere in government. I agree. My comments in these posts apply only to explicit budgeting decisions, like those in 2010’s health reform or today’s student loan legislation. In that context, Social Security savings cannot be legislatively used to pay for other programs. But they still might have indirect effects. For example, by reducing future unified budget deficits, Social Security savings might weaken future congressional efforts to reduce deficits outside Social Security.

Energy Security, the Infographic

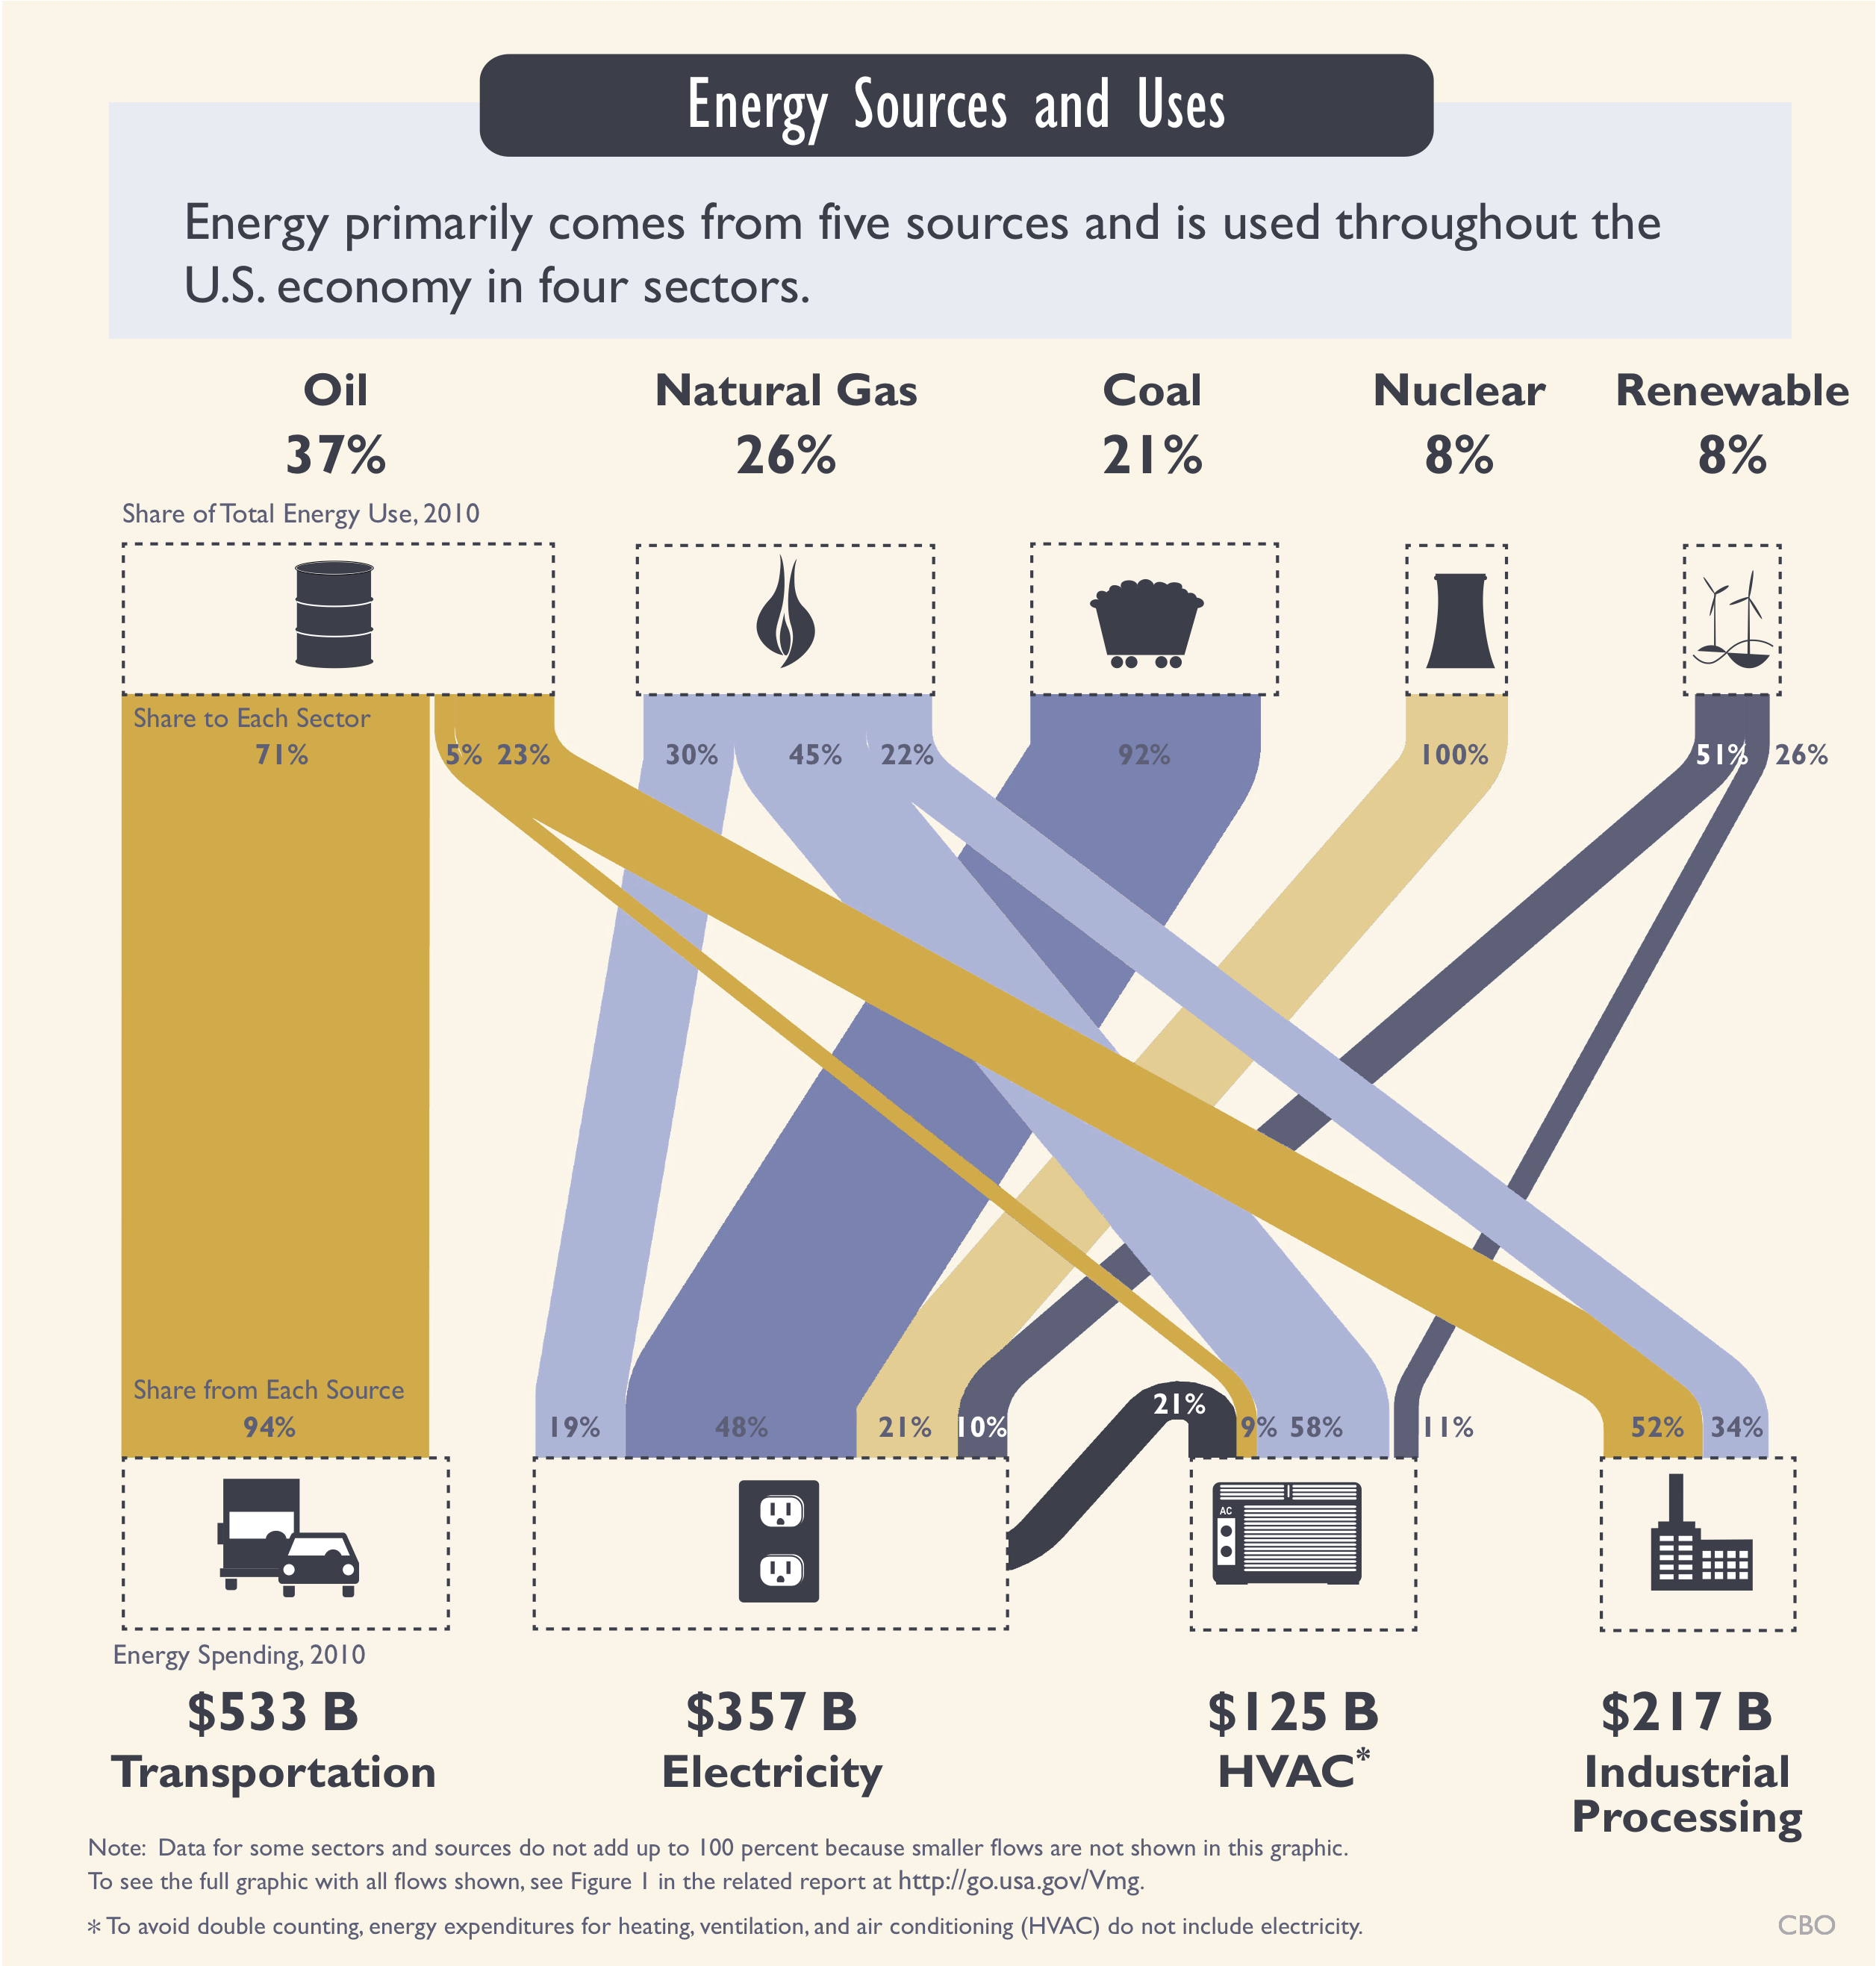
The Congressional Budget Office is out with another fine infographic, this time on energy security.

The entire infographic is too big to post here, but here’s how Andrew Stocking and Maureen Costantino portray America’s energy sources and uses:

One of the most notable features is the absence of any link from natural gas to transportation (some natural gas is used in transportation, of course, but not enough to make the cut for this image). Given the ever-growing divergence between oil and natural gas prices, I wonder whether that will still be true a decade from now? Or will someone finally crack the natural gas to transportation fuel market in a big way?

The Fight over Medicare Double Counting

The recent double-counting dispute isn’t just about politics; it also reveals a flaw in budgeting for Medicare Part A.

Budget experts are waging a spirited battle over the Medicare changes that helped pay for 2010’s health reform. In April, Chuck Blahous, one of two public trustees of the program, released a study arguing that the Affordable Care Act (ACA) would increase the deficit by at least $340 billion by 2021, a sharp contrast from the $210 billion in deficit reduction estimated by the Congressional Budget Office (CBO).

Chuck bases his estimates on several factors, but the item that has garnered the most attention is his charge that the ACA’s spending cuts and revenue increases in Medicare Part A are being double counted: once to help pay for the ACA’s coverage expansion and a second time to improve the finances of the Part A trust fund, whose predicted exhaustion was delayed by several years.

Chuck notes that those resources can be used only once: They can either offset some costs of health reform or strengthen Medicare, but not both. He believes those resources will ultimately finance additional Medicare spending and thus can’t offset any health reform costs. For that reason, he concludes that the ACA would increase deficits, rather than reduce them.

That argument inspired a host of commentary from leading budget experts, ranging from denunciation to affirmation. See, for example, Jeffrey Brown, Howard Gleckman, Peter Orszag, Robert Reischauer (as quoted by Jonathan Chait), and Paul Van de Water, and a follow up by Chuck and Jim Capretta.

Why does this dispute exist? It can’t just be politics. If it were, we’d have double-counting disputes about every program. But we don’t. We thus need an explanation for why this debate has erupted around Medicare Part A, which provides hospital insurance, but not around other programs. Part A is not unique in controlling spending by a “belt and suspenders” combination of regular program rules (the “belt”) and an overall limit (the “suspenders”). Such budgeting also applies to Social Security, Medicare Parts B and D (which cover physician visits and prescription drugs), and the National Flood Insurance Program. The federal debt limit acts as “suspenders” for the entire budget. But none of those give rise to double-counting disputes.

That suggests that there is something unusual—perhaps flawed—about budgeting for Medicare Part A. To see what that is, it helps to boil the dispute down to two basic questions about programs subject to “belt and suspenders” budgeting.
First, can spending reductions or revenue increases in the program offset spending increases or revenue reductions in other programs? In short, can budget savings pay for other programs? Or must they stay within the program itself?

Second, would hitting the overall budget limit affect program operations? In other words, do budget savings extend the period during which the program can operate at full capacity? Or is the limit operationally toothless?

As shown above, policymakers have answered these questions differently for different programs (for further details, see the appendix).

This comparison reveals the unique feature of Medicare Part A: It is the only one of these programs that allows budget savings to pay for other programs and has a trust fund with real operational teeth. It alone answers Yes to both questions. That is why Medicare Part A is the only program that creates the possibility of double counting and suffers from the reality of a double-counting dispute.

Double counting isn’t possible in Social Security or the NFIP because budget rules require that savings stay in the program. It isn’t possible for the budget as a whole since there are, by definition, no other programs to fund. And double counting isn’t possible in Medicare Parts B and D because its trust fund does nothing to limit operations.

But double counting is possible in Medicare Part A. That happens whenever someone claims that the health reform legislation both reduces deficits and provides additional resources to Medicare Part A. I will leave it to others to adjudicate whether any health reform proponents committed that error. I will note, however, that every budget expert, including Chuck Blahous, agrees that CBO didn’t do so (its baseline ignores the trust fund, so savings reduce deficits and have no effect on program operations).

Bottom line: The peculiar budget rules for Medicare Part A make it possible for analysts, pundits, and policymakers—whether willfully or inadvertently—to double count budget savings in Medicare Part A. That needless confusion is a significant flaw. To correct it, Congress could adopt the budget practices it uses in Social Security, Medicare B & D, or the NFIP. In a follow-up post, I will examine the pros and cons of these alternatives.

 Appendix: How “Belt and Suspenders” Budgeting Works

Continue reading “The Fight over Medicare Double Counting”

Why Free is a Bad Price, American Airlines Edition

Companies often run into trouble when they offer a service at a zero price.

Not always, of course. Many all-you-can-eat buffets continue to thrive even though the marginal cost of the next chicken nugget is zero. And many content providers manage to stay in business by selling radio, TV, or display ads against the free content users enjoy.

But all too often, a zero price attracts bad customers and encourages excessive consumption. Marco Arment of Instapaper, for example, discovered that a zero price attracted “undesirable customers” for his app. And AT&T famously discovered that offering unlimited iPhone data could overwhelm its capacity.

Thanks to Ken Besinger of the Los Angeles Times, we now have another juicy example: the lifetime passes that American Airlines sold to a small group of customers:

There are frequent fliers, and then there are people like Steven Rothstein and Jacques Vroom.

Both men bought tickets that gave them unlimited first-class travel for life on American Airlines. It was almost like owning a fleet of private jets.

Passes in hand, Rothstein and Vroom flew for business. They flew for pleasure. They flew just because they liked being on planes. They bypassed long lines, booked backup itineraries in case the weather turned, and never worried about cancellation fees. Flight crews memorized their names and favorite meals.

Each had paid American more than $350,000 for an unlimited AAirpass and a companion ticket that allowed them to take someone along on their adventures. Both agree it was the  best purchase they ever made, one that completely redefined their lives. …

But all the miles they and 64 other unlimited AAirpass holders racked up went far beyond what American had expected. As its finances began deteriorating a few years ago, the carrier took a hard look at the AAirpass program.

Heavy users, including Vroom and Rothstein, were costing it millions of dollars in revenue, the airline concluded.

How did things go wrong? American Airlines miscalculated how pass holders would behave:

“We thought originally it would be something that firms would buy for top employees,” said Bob Crandall, American’s chairman and chief executive from 1985 to 1998. “It soon became apparent that the public was smarter than we were.”

In economic jargon, American fell victim to both adverse selection and moral hazard. What customer wants to buy an unlimited, lifetime pass? One who’s happy to spend a great deal of time flying about in first class with friends, family members, or a random person they just met at the gate. And how will they behave? As though first class seats are costless, easy to book, free to cancel, a great gift for friends and strangers, and even, in some cases, as a revenue source.

What happened next shouldn’t be surprising. First, the passes went through a death spiral with American raising the price in a vain effort to make them profitable. When last offered, a single pass cost $3 million and was purchased by a grand total of nobody. Second, American sicced its “revenue management executives” on the most flagrant of the frequent flyers. As a result, several had their passes revoked for misuse. And American faces some lawsuits that make one wonder whether it crossed the line in trying to rid itself of these outrageously expensive customers.

Jobs Report – The Soft Side of Mediocre

As expected, today’s jobs data showed a slowing labor market. Payrolls expanded by 115,000 in April, less than hoped or expected. Upward revisions to February and March added another 53,000 jobs, however, so the overall payroll picture is better than the headline. The unemployment rate ticked down to 8.1%, the labor force participation rate slipped to 63.6%, weekly hours were unchanged at 34.5, and hourly earnings increased a measly penny from $23.37 to $23.38.

Put it all together, and this report is on the soft side of mediocre.

Unemployment and underemployment both remain very high, but they’ve been moving in the right direction. After peaking at 10% in October 2009, the unemployment rate has declined by about 2 percentage points. The U-6 measure of underemployment, meanwhile, peaked at 17.2% and now stands at 14.5%:

(The U-6 measures includes the officially unemployed, marginally attached workers, and those who are working part-time but want full-time work.)

Investing in Memories, Ocelot Edition

A recurring theme of recent happiness research is that when it comes to seeking pleasure, people should “buy experiences rather than things.” People are happier when they skip the shiny baubles (or new high heels) and do something memorable.

Over at the Atlantic, Garett Jones gives one economic explanation for this finding: memories are a durable good.

[M]emory, wholly intangible, is quite durable.

People often shrink from driving to a distant, promising restaurant, flying to a new country, trying a new sport–it’s a hassle, and the experience won’t last that long. That’s the wrong way to look at it. When you go bungee jumping, you’re not buying a brief experience: You’re buying a memory, one that might last even longer than a good pair of blue jeans.

Psych research seems to bear this out: People love looking forward to vacations, they don’t like the vacation that much while they’re on it, and then they love the memories. Most of the joy–the utility in econospeak–happens when you’re not having the experience. …

[P]eople treat memories somewhat like durables, but most of us could do a better job of it. Yes, it’ll be a hassle to find that riad in Marrakech when your GPS fails you, but complaining about it with your sibling years later will be a ton of fun. Get on with it.

A corollary: if memory really is a durable, then you should buy a lot of it when you’re young. That’ll give you more years to enjoy your purchase.

So it’s worth a bit of suffering to create some good memories, since the future lasts a lot longer than the present.

That’s good advice. But I can’t help thinking that people who are unhappy on vacation are doing it wrong. Then again, maybe my recollection is blurred by selective memory?

In any case, the little feline above is a great example of Garett’s thesis. Since I was a child, I had always wanted to see an ocelot in the wild. And last summer, Esther and I found one in Brazil. Our entire encounter lasted about 15 seconds and produced a couple of mediocre photos. But until my brain gives out, I will always cherish seeing the little critter.

P.S. About 20 years ago, I recall someone attributing the “memory is a durable good” idea to Milton Friedman. If anyone’s got a cite to that, please post in the comments.

P.P.S. Will Wilkinson also comments on Garett’s thesis.

Advanced Game Theory, Golden Balls Edition

My Twitter feed is, quite rightly, full of links to this remarkable episode of Golden Balls, the British game show that puts contestants in a classic game theory dilemma of “splitting or stealing” the grand prize:

If you have time for more, here’s another famous episode, with a very different display of strategy and tactics:

Entitlement Spending in One Picture

Here’s another fun infographic by CBO’s Jonathan Schwabish and Courtney Griffith. This one surveys all the mandatory spending programs (aka entitlements) in the federal budget and how they have changed over the past two decades:

P.S. In case you missed it, here’s Jon and Courtney’s overview of the entire federal budget. They also have nice graphics on discretionary spending and federal revenues.